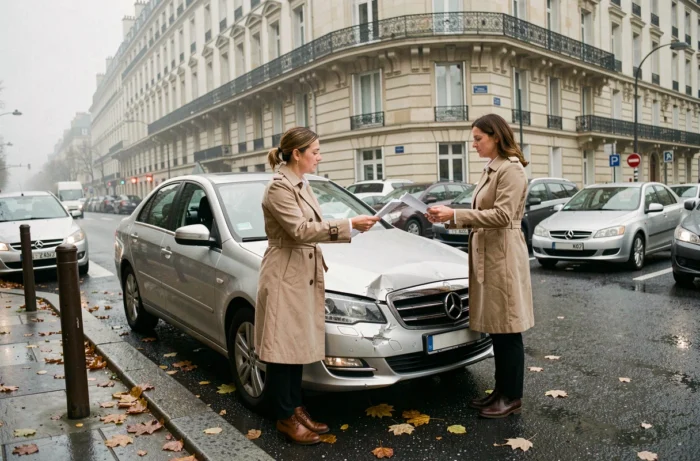
After a crash or collision in Paris, most victims know they are entitled to compensation. What they are less aware of is the strict timeline to adhere to and the importance of each document produced in the first weeks. A poorly constructed file from the start can significantly reduce the final amount paid by the insurer, even when the other driver’s liability is beyond doubt.
Legal deadlines for road accident compensation: what the Badinter law really imposes
The law of July 5, 1985 (known as the Badinter law) does not merely create a right to compensation. It sets precise deadlines that the insurer of the involved vehicle must respect.
The insurer is required to make a compensation offer within a specified timeframe from the request. However, the lesser-known part of the system concerns what happens after the offer: the victim has 15 days to withdraw after accepting a proposal. This withdrawal period, provided by law, allows for a reconsideration of an agreement signed too hastily, for example, under the pressure of an expert appointed by the insurance.
Another step to monitor: once the offer is definitively accepted, the insurer has 45 days to pay the funds. Knowing this deadline helps avoid confusing the principle agreement with the actual settlement.
To understand how to obtain road accident compensation in Paris, it is essential to incorporate these two deadlines from the outset: they dictate the pace of the entire file.
Medical expertise and bodily injury: the moment that determines the amount
The medical expertise is not a formality. It is the appointment that almost entirely determines the amount of compensation for bodily injuries. The expert doctor evaluates each item of damage: suffering endured, functional deficit, aesthetic damage, professional impact.
Have you received a summons from the opposing insurer for an expertise? This doctor is appointed (and paid) by the insurance company. Their report will guide the compensation offer. This is why attending this examination alone is risky.
Preparing for the expertise to protect your rights
Being accompanied by an independent medical advisor changes the game. This practitioner, chosen by the victim, attends the examination and can contest the ratings made by the insurance expert.
Before the day of the expertise, gather all medical documents in chronological order:
- The initial medical certificate issued at the emergency room or by the attending physician, which describes the injuries observed on the day of the accident
- The hospitalization reports, imaging (X-rays, MRIs), and rehabilitation prescriptions
- The successive work stoppages and, if applicable, letters from the occupational physician certifying temporary or permanent unfitness
- Unreimbursed care invoices (psychologist, osteopath, home help)
A complete and chronological medical file increases the credibility of the damage items. Conversely, missing documents leave the opposing expert free to minimize the assessment.
Insurer’s compensation offer: why the first proposal is rarely the right one
The insurer of the involved vehicle is legally required to present an offer. This offer generally covers all the damages identified during the expertise. In practice, the first offer often undervalues several items of damage.
The items most frequently undervalued are the permanent functional deficit (when the retained rate is low), the suffering endured, and the loss of enjoyment, meaning the loss of the ability to engage in leisure activities. The insurer applies its own internal scales, which do not correspond to the amounts awarded by the courts.
Negotiate or contest in court
Two paths exist after receiving the offer. The amicable procedure involves negotiating directly with the insurer, ideally with the support of a lawyer specialized in bodily injury. The civil procedure, before the judicial court, allows for compensation determined by a judge.
Accepting an offer without comparing it to legal benchmarks is the most costly mistake. A lawyer can compare each item to the amounts usually retained by Parisian courts, which serve as a reference for evaluating whether the offer is correct.
The choice between amicable procedure and civil procedure depends on the gap between the offer and the actual assessment. When the gap remains moderate, negotiation is often sufficient. When the insurer refuses to reassess a documented item of damage, going before the judge becomes the only option for obtaining full compensation.
Pedestrians, passengers, and cyclists in Paris: a more protective compensation system
The Badinter law clearly distinguishes the driver from other victims. Pedestrians, passengers, and cyclists benefit from full compensation for their bodily injuries, regardless of the liability of the involved driver.
The only exception provided by law concerns the victim who has voluntarily sought the damage. Outside of this extreme case, a pedestrian knocked down at a Parisian intersection or a passenger injured in a collision is entitled to full compensation for their damages, even if they acted recklessly.
For the driver, the situation is different. Compensation for their own injuries depends on their share of responsibility in the accident and the coverage taken out in their insurance contract. Two types of coverage come into play: liability insurance (mandatory, but which does not cover the injuries of the responsible driver) and driver’s coverage, optional, which covers their bodily injuries.
Checking their insurance contract before starting the procedures avoids unpleasant surprises. A partially responsible driver who has not taken out driver’s coverage may find themselves without any coverage for their own injuries.
The compensation file after an accident in Paris follows a precise sequence: reporting within deadlines, compiling the medical file, adversarial expertise, analyzing the offer. Each step conditions the next. Skipping or rushing through any of them mechanically reduces the final amount. The quality of the initial file weighs more than the duration of the procedure.


